NEWS
NEWS
Agentic Payments: Real Shift or Hype, and What Should Fintechs Do About It?
Agentic Payments: Real Shift or Hype, and What Should Fintechs Do About It?

AI agents are becoming increasingly capable of handling shopping and payments tasks that traditionally required a human hand behind the wheel. But whether consumer trust is keeping up with the tech is a completely different question.
Payment giants like Visa and Mastercard are already neck-deep in introducing tools for AI-powered transactions – as well as tools to manage relevant risks. Yet Visa's research also found that only 23% of U.S. consumers actually trust gen AI to handle payments on their behalf.
So are agentic payments truly about to change how we spend money? Or is the industry getting ahead of itself?
Drofa Comms spoke with three female leaders in fintech to try and find the answer.
Adoption Takes Time
Agentic payments are a real shift, but they mean more than just another way to automate online shopping. They introduce an entirely different approach to commerce, where customers delegate purchasing decisions to a piece of software.
Jackie Swanson, Managing Partner at Gartner Consulting, sees this as a structural change. Instead of personally searching for products and comparing options, consumers can now let AI agents handle all these tasks in their place. And then also pay for the purchase.
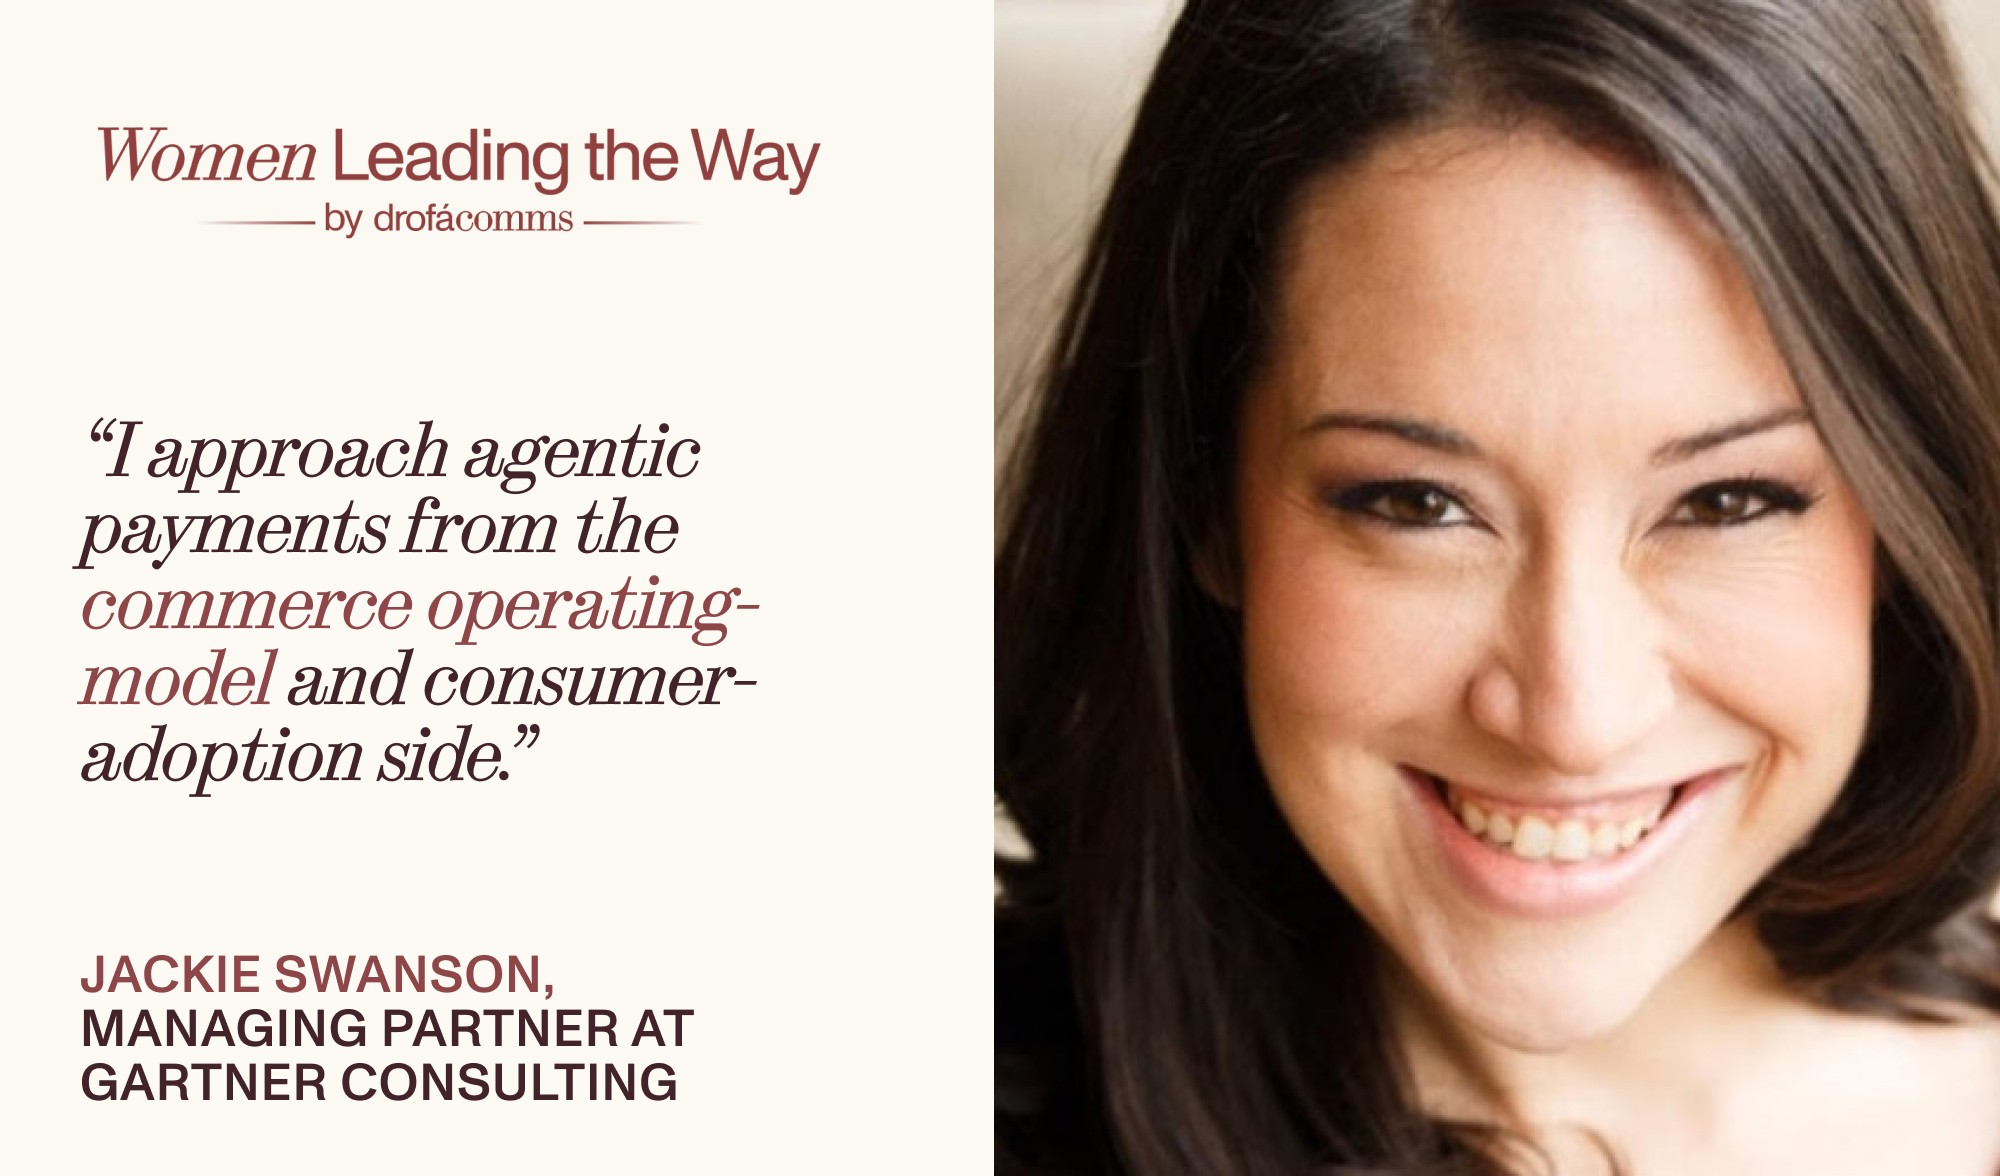
However, she also believes adoption will not happen all at once. Consumers are more likely to start by delegating routine activities. Control over expensive or emotionally significant transactions won’t be given over to agents just yet.
“Trust will grow task by task, beginning with low-value, repeatable transactions where the customer defines the merchant, category, amount and timing.”
Meanwhile, Annabelle Huang, Co-founder and CEO of Altius Labs, has a more cautious outlook. She believes agentic payments could potentially change a lot, but for now, there are still too many unanswered questions. Not least of which is how much financial autonomy people are willing to give AI in the first place.

As she points out, all the noise surrounding artificial intelligence makes it difficult to distinguish genuine changes in consumer behaviour from general hype and expectations of where the technology might eventually go.
"The potential is significant, but the hype makes the timeline and eventual scale difficult to judge," Huang explains.
The Priority Is Building Controlled Infrastructure
So then, if consumer adoption is still in the early stages, it leads to a question: “What should fintech companies be doing now?”
For Swanson, the priority is to build the infrastructure that makes delegated payments safer and more manageable. This means that payment systems need to be able to verify an agent's identity and recognise that a customer has indeed given their authorisation.
Naturally, keeping clear audit records of all transactions is also paramount. Not to mention reliable fraud monitoring, clear responsibility for dispute cases, and the ability to stop transactions immediately when something goes wrong. In other words, there’s a lot of work ahead for those companies.
Jackie recommends starting with one clearly defined use case and measure how it performs. Fintechs don't need to automate every payment process at once. First, they’re better off understanding how to make a limited form of automation work reliably and adjusting as they go.
Annabelle similarly cautions against overcommitting. She believes it premature to invest heavily in such products based just on assumptions about what future consumer behaviour could be like.
Why Payment Infrastructure Matters
For Veni Dhir, Director at ADP Ventures, the technology itself isn't the main obstacle to adoption. She believes agentic payments are a genuine shift, but argues that the timeline suggested by many industry demonstrations is simply too unrealistic.

The reason, as she puts it, is straightforward: “Moving money is thehighest-stakes action an AI agent can perform.” So if a transaction goes wrong, companies need to know who is responsible for the loss, how the team can unwind it, and how the entire process can be audited.
As such, the companies addressing these challenges will be particularly important to the further development of this sector. Programmable spending limits, real-time ledgering, reliable APIs that prevent duplicate transactions – all of this and more will be necessary if payment providers wish to make agentic payments auditable. And they will need to be auditable for trust to grow.
Dhir believes that for enterprise customers to be truly engaged, fintechs first need to sell them on demonstrable control and reliability, not just automation.
What If Your Fintech Doesn't Have the Budget to Experiment?
It has to be acknowledged that not every company has the resources to build dedicated AI teams or launch experimental projects without any promise of payoffs. But that also doesn't mean smaller fintechs can’t move on the agentic payments agenda at all.
Swanson suggests that even a company with limited resources can take some practical steps. Running a small pilot with one or two people to coordinate the work is possible. And there’s no need to build bespoke infrastructure when emerging payment network standards can provide all the necessary capabilities instead.
Huang, meanwhile, believes that waiting on this is also perfectly reasonable. Being the first to market isn't necessarily an advantage if you're building something customers don't actually need.
Smaller companies can focus on keeping their infrastructure adaptable, monitor emerging standards, and watch for genuine signs of customer demand. Early deployments will reveal which use cases deliver practical value – and that’s when fintechs will have better information to guide their investments.
Conclusion
All in all, agentic payments have the potential to change how people interact with financial services, but the development of this technology should not be confused with widespread consumer adoption.
The future of agentic payments will depend not only on what AI agents can do, but on whether consumers and businesses are comfortable trusting them with their money.
For fintechs, the immediate opportunity isn't necessarily to launch fully autonomous payment products. It's to make existing infrastructure ready for a world where more transactions may be initiated by software. Companies with fewer resources can take smaller steps and wait for clearer evidence of demand before making any significant moves.
Acknowledgements: Drofa Comms would like to thank Jackie Swanson, Annabelle Huang, and Veni Dhir for sharing their insights and contributing to this article.
AI agents are becoming increasingly capable of handling shopping and payments tasks that traditionally required a human hand behind the wheel. But whether consumer trust is keeping up with the tech is a completely different question.
Payment giants like Visa and Mastercard are already neck-deep in introducing tools for AI-powered transactions – as well as tools to manage relevant risks. Yet Visa's research also found that only 23% of U.S. consumers actually trust gen AI to handle payments on their behalf.
So are agentic payments truly about to change how we spend money? Or is the industry getting ahead of itself?
Drofa Comms spoke with three female leaders in fintech to try and find the answer.
Adoption Takes Time
Agentic payments are a real shift, but they mean more than just another way to automate online shopping. They introduce an entirely different approach to commerce, where customers delegate purchasing decisions to a piece of software.
Jackie Swanson, Managing Partner at Gartner Consulting, sees this as a structural change. Instead of personally searching for products and comparing options, consumers can now let AI agents handle all these tasks in their place. And then also pay for the purchase.
However, she also believes adoption will not happen all at once. Consumers are more likely to start by delegating routine activities. Control over expensive or emotionally significant transactions won’t be given over to agents just yet.
“Trust will grow task by task, beginning with low-value, repeatable transactions where the customer defines the merchant, category, amount and timing.”
Meanwhile, Annabelle Huang, Co-founder and CEO of Altius Labs, has a more cautious outlook. She believes agentic payments could potentially change a lot, but for now, there are still too many unanswered questions. Not least of which is how much financial autonomy people are willing to give AI in the first place.
As she points out, all the noise surrounding artificial intelligence makes it difficult to distinguish genuine changes in consumer behaviour from general hype and expectations of where the technology might eventually go.
"The potential is significant, but the hype makes the timeline and eventual scale difficult to judge," Huang explains.
The Priority Is Building Controlled Infrastructure
So then, if consumer adoption is still in the early stages, it leads to a question: “What should fintech companies be doing now?”
For Swanson, the priority is to build the infrastructure that makes delegated payments safer and more manageable. This means that payment systems need to be able to verify an agent's identity and recognise that a customer has indeed given their authorisation.
Naturally, keeping clear audit records of all transactions is also paramount. Not to mention reliable fraud monitoring, clear responsibility for dispute cases, and the ability to stop transactions immediately when something goes wrong. In other words, there’s a lot of work ahead for those companies.
Jackie recommends starting with one clearly defined use case and measure how it performs. Fintechs don't need to automate every payment process at once. First, they’re better off understanding how to make a limited form of automation work reliably and adjusting as they go.
Annabelle similarly cautions against overcommitting. She believes it premature to invest heavily in such products based just on assumptions about what future consumer behaviour could be like.
Why Payment Infrastructure Matters
For Veni Dhir, Director at ADP Ventures, the technology itself isn't the main obstacle to adoption. She believes agentic payments are a genuine shift, but argues that the timeline suggested by many industry demonstrations is simply too unrealistic.
The reason, as she puts it, is straightforward: “Moving money is thehighest-stakes action an AI agent can perform.” So if a transaction goes wrong, companies need to know who is responsible for the loss, how the team can unwind it, and how the entire process can be audited.
As such, the companies addressing these challenges will be particularly important to the further development of this sector. Programmable spending limits, real-time ledgering, reliable APIs that prevent duplicate transactions – all of this and more will be necessary if payment providers wish to make agentic payments auditable. And they will need to be auditable for trust to grow.
Dhir believes that for enterprise customers to be truly engaged, fintechs first need to sell them on demonstrable control and reliability, not just automation.
What If Your Fintech Doesn't Have the Budget to Experiment?
It has to be acknowledged that not every company has the resources to build dedicated AI teams or launch experimental projects without any promise of payoffs. But that also doesn't mean smaller fintechs can’t move on the agentic payments agenda at all.
Swanson suggests that even a company with limited resources can take some practical steps. Running a small pilot with one or two people to coordinate the work is possible. And there’s no need to build bespoke infrastructure when emerging payment network standards can provide all the necessary capabilities instead.
Huang, meanwhile, believes that waiting on this is also perfectly reasonable. Being the first to market isn't necessarily an advantage if you're building something customers don't actually need.
Smaller companies can focus on keeping their infrastructure adaptable, monitor emerging standards, and watch for genuine signs of customer demand. Early deployments will reveal which use cases deliver practical value – and that’s when fintechs will have better information to guide their investments.
Conclusion
All in all, agentic payments have the potential to change how people interact with financial services, but the development of this technology should not be confused with widespread consumer adoption.
The future of agentic payments will depend not only on what AI agents can do, but on whether consumers and businesses are comfortable trusting them with their money.
For fintechs, the immediate opportunity isn't necessarily to launch fully autonomous payment products. It's to make existing infrastructure ready for a world where more transactions may be initiated by software. Companies with fewer resources can take smaller steps and wait for clearer evidence of demand before making any significant moves.
Acknowledgements: Drofa Comms would like to thank Jackie Swanson, Annabelle Huang, and Veni Dhir for sharing their insights and contributing to this article.
London office
Rise, created by Barclays, 41 Luke St, London EC2A 4DP
Nicosia office
2043, Nikokreontos 29, office 202
DP FINANCE COMM LTD (#13523955) Registered Address: N1 7GU, 20-22 Wenlock Road, London, United Kingdom For Operations In The UK
AGAFIYA CONSULTING LTD (#HE 380737) Registered Address: 2043, Nikokreontos 29, Flat 202, Strovolos, Cyprus For Operations In The EU, LATAM, United Stated Of America And Provision Of Services Worldwide
Drofa © 2024
